Meta Platforms Inc. stocks have been trading down by -2.66 percent amid heightened regulatory scrutiny and antitrust concerns dampening investor sentiment.
Key Takeaways For META Traders
- Oppenheimer flags roughly $135B in projected AI/Muse-driven free cash flow losses for META through 2028, above its about $90B cash and securities and raising equity-raise risk.
- A U.S. jury finding that META misled users in the Cambridge Analytica scandal exposes the company to potential penalties in the $35–$40B range.
- A New Mexico court reportedly ordering META to pay $25B over data privacy violations marks a sharp escalation in the company’s legal liabilities.
- The EU is weighing a new lump-sum tax on large firms, directly targeting U.S. tech names like META and tightening the cost vise in Europe.
- A Florida social-media law barring kids under 14 from apps such as Instagram adds another regulatory hit to META’s user growth and engagement story.
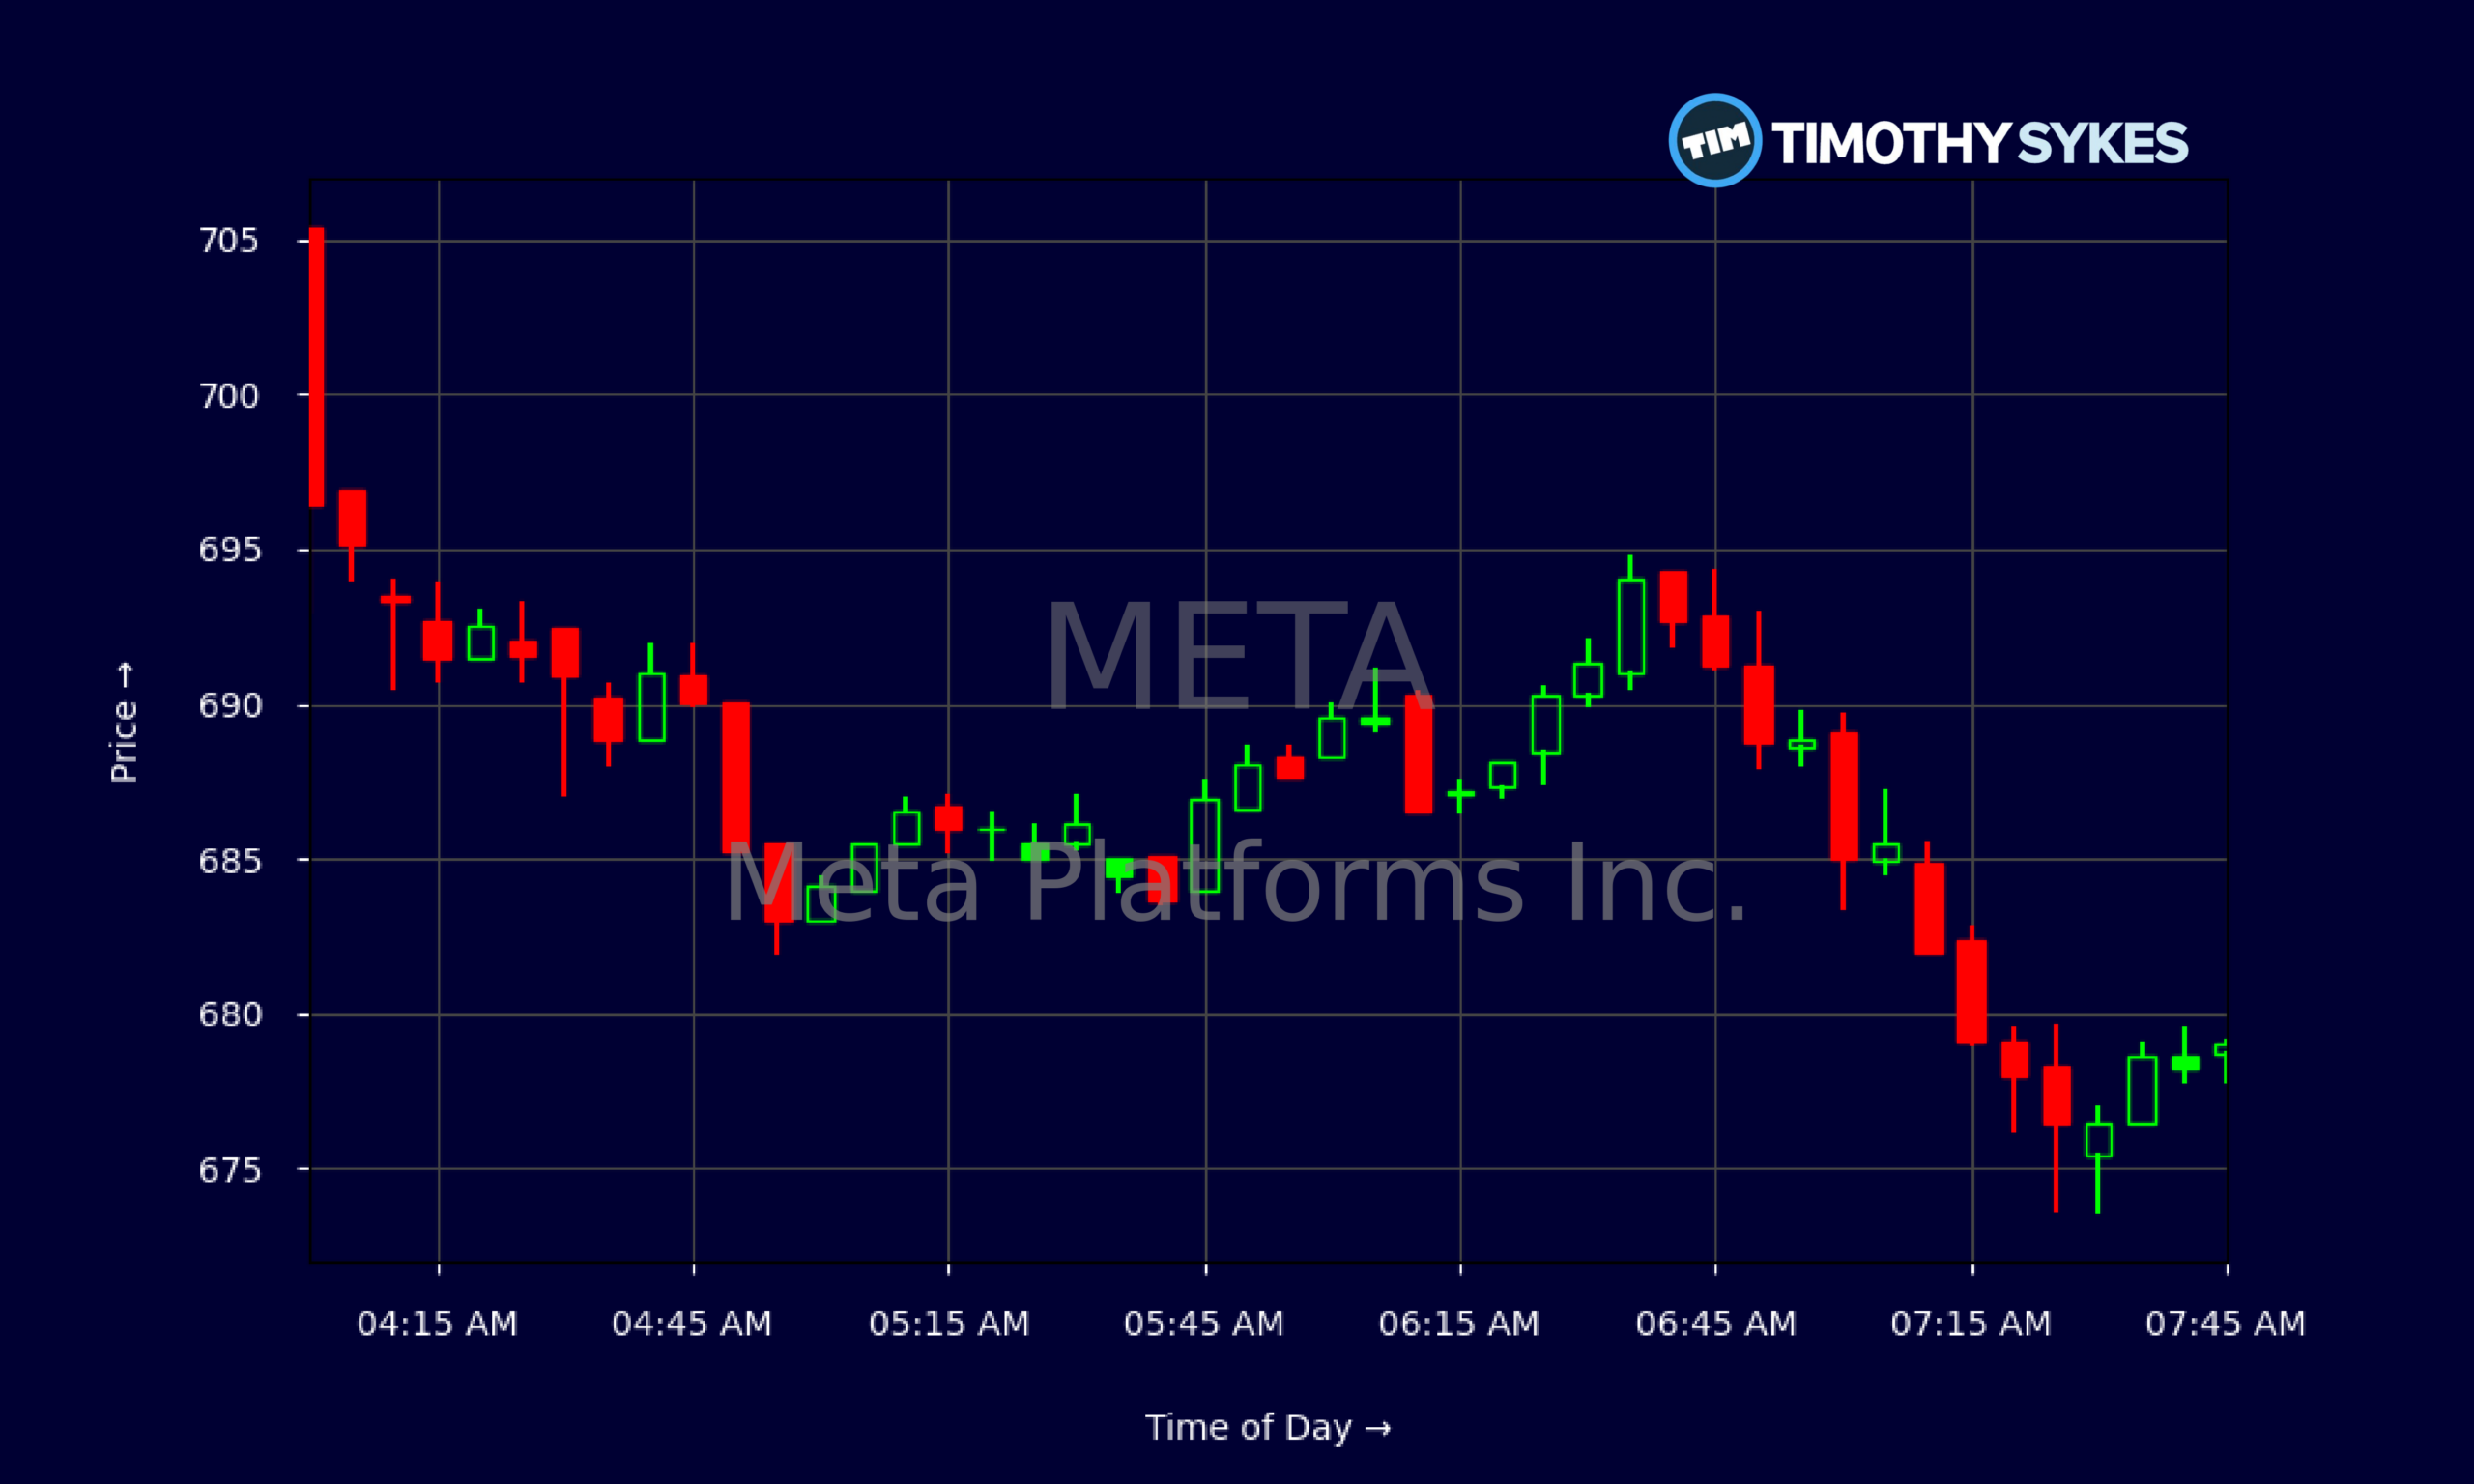
Live Update At 07:48:06 EDT: On Thursday, October 22, 2026 Meta Platforms Inc. stock [NASDAQ: META] is trending down by -2.66%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
META has been grinding lower on the daily chart. From a recent swing high near the mid-$760s, META has slipped into the high-$690s, breaking below several short-term support levels. The 2026/10/21 session closed around $697.52 after testing both $713.22 on the upside and $689.68 on the downside, showing wide intraday ranges and clear two-sided trading.
Zooming out, META’s fundamentals still look powerful at first glance. Quarterly revenue of about $60.8B and EBITDA near $25.9B show a machine that still prints cash from its core ad business. Profitability is strong, with EBIT margin above 36% and net margin close to 30%. Return on equity near 30% signals META is using shareholder capital efficiently.
More Breaking News
But traders need to line those strengths up against valuation and cash demands. A P/E around 27 and price-to-sales near 8 place META firmly in premium territory while price-to-free-cash near 262 screams market expectations for future growth. At the same time, META’s Q2 free cash flow was only about $1.75B, heavily pressured by roughly $30.1B in capital expenditure. The balance sheet is solid, with a current ratio above 2 and interest coverage over 150, but rising debt and massive AI spend mean the margin for error is shrinking.
Why Traders Are Watching META Right Now
META is sitting at the intersection of three forces: heavy AI spending, explosive legal liabilities, and mounting regulation. That mix is what real traders live for, but it demands discipline.
On the spending side, Oppenheimer’s neutral call on META landed like a warning flare. The firm sees around $135B in cumulative free cash flow losses through 2028 tied to META’s AI and Muse build-out, against roughly $90B of cash and securities. For traders, that matters more than the “neutral” label. It says META’s AI push is not a gentle capex cycle; it is an all-in cash burn that might force an equity raise ahead of the Anthropic IPO. Equity raises usually mean dilution, EPS resets, and, often, multiple compression. For a name already trading around 27x earnings, that’s serious rerating risk.
Layered on top is the Cambridge Analytica overhang. A U.S. jury finding META misled users has opened the door to $35–$40B in potential penalties. New Mexico is pushing the judge to throw the book at the company, and a court there has reportedly ordered META to pay $25B tied to state law violations. Even if appeals drag this out or cut the final bill, traders have to respect headline risk. Any new ruling or enforcement step can gap META sharply, in either direction.
Meanwhile, regulation is closing in from multiple angles. The EU is considering a broad annual lump-sum tax on large companies with more than EUR 100M in EU revenue, explicitly aimed at big U.S. tech, META included. That threatens to chip away at European margins for years. In the U.S., a Florida law now blocks kids under 14 from using platforms like Instagram and targets “addictive” features such as autoplay and infinite scroll. If other states follow, META’s growth funnel for younger users could tighten just as Wall Street is watching engagement metrics more closely.
All of this is happening against a macro backdrop of high Treasury yields and risk-off trading across growth names. META has already shown it is not immune, trading down about 2.5% premarket on one recent session as retail favorites sold off together. For active traders, META is no longer just a mega-cap trend ride. It is a headline-driven, macro-sensitive battleground.
Conclusion
META now trades like a heavyweight that must keep swinging. The company still throws off huge revenue and strong operating margins, but the story is shifting from “clean growth” to “can the cash engine outrun the legal and AI bill?” With free cash flow squeezed by roughly $30B in quarterly capex, and Wall Street modeling years of negative cumulative free cash flow, traders cannot ignore balance-sheet strategy anymore. Any concrete talk of an equity raise or sharper expense guide for 2027 and beyond will be key catalysts.
At the same time, META’s legal and regulatory tape is stacked with land mines. A reported $25B order out of New Mexico, potential $35–$40B maximum penalties tied to Cambridge Analytica, EU tax plans, and U.S. state-level rules like Florida’s social-media law all press on the same pressure point: META’s margins and growth runway. Yet price action has been oddly resilient at times, with META trading higher on some of the worst legal headlines as traders bet on appeals and negotiated outcomes.
For the Tim Sykes crowd, this is where preparation pays. The chart is choppy, the news is binary, and the crowd is often late. As Tim Sykes likes to remind traders, “The market rewards those who are prepared, not those who are lucky.” As millionaire penny stock trader and teacher Tim Sykes, says, “It’s better to go home at zero than to go home in the red.”. For META, that means having a plan for both sharp squeezes and rug pulls, focusing on levels, liquidity, and how each new headline actually shifts the risk-reward, not just the noise. This content is produced strictly for educational and research purposes and is not investment advice.
This is stock news, not investment advice. Timothy Sykes News delivers real-time stock market news focused on key catalysts driving short-term price movements. Our content is tailored for active traders and investors seeking to capitalize on rapid price fluctuations, particularly in volatile sectors like penny stocks. Readers come to us for detailed coverage on earnings reports, mergers, FDA approvals, new contracts, and unusual trading volumes that can trigger significant short-term price action. Some users utilize our news to explain sudden stock movements, while others rely on it for diligent research into potential investment opportunities.
Dive deeper into the world of trading with Timothy Sykes, renowned for his expertise in penny stocks. Explore his top picks and discover the strategies that have propelled him to success with these articles:
- Penny Stocks Trading Guide
- Best Penny Stocks Under $1 to Buy Today
- Top 8 Penny Stocks to Watch on Robinhood
Once you’ve got some stocks on watch, elevate your trading game with StocksToTrade the ultimate platform for traders. With specialized tools for swing and day trading, StocksToTrade will guide you through the market’s twists and turns.
Dig into StocksToTrade’s watchlists here:
Leave a reply